How China Took Control of the World’s Rare Earths
Already in 1987, China’s then-leader Deng Xiaoping declared: “While the Middle East has oil, China has rare earths.” The statement summarized a strategy that had been unfolding for more than a decade. During the 1980s and 1990s, China combined abundant reserves, low production costs, and weak environmental regulations to gradually outcompete other producers and consolidate control over the global rare earth market.
In the 2000s, exports surged. Rare earths flooded global markets at prices far below Western production costs. Many mines in the United States, Australia, and Europe were forced to close, and China established a dominant position in production and refining.
The power imbalance became evident in 2010, when a Chinese fishing captain was detained near the disputed Senkaku Islands. In the wake of the crisis China suspended rare earth exports to Japan. This was a disruption that revealed how quickly a political conflict could reverberate through global industrial supply chains.
The Rise of China’s Resource Regime
Since the mid-2010s, this dominance has evolved into a system of state control. Between 2015 and 2018, the sector was consolidated into six chines state-owned conglomerates, ostensibly to combat illegal mining and strengthen environmental standards, but also to enable centralized management.
The 2018–2020 trade conflict with the United States accelerated this process. U.S. tariffs, sanctions against Huawei, and the first American export controls on semiconductor technology led China to reclassify rare earths as a strategic asset.
In 2021, the state merged several major producers to form China Rare Earth Group, concentrating the production of medium and heavy rare earths under a single state-owned enterprise. New environmental, export, and data-reporting rules followed in 2022–2023, and as U.S.–China rivalry intensified, the official rhetoric increasingly adopted a national security tone.
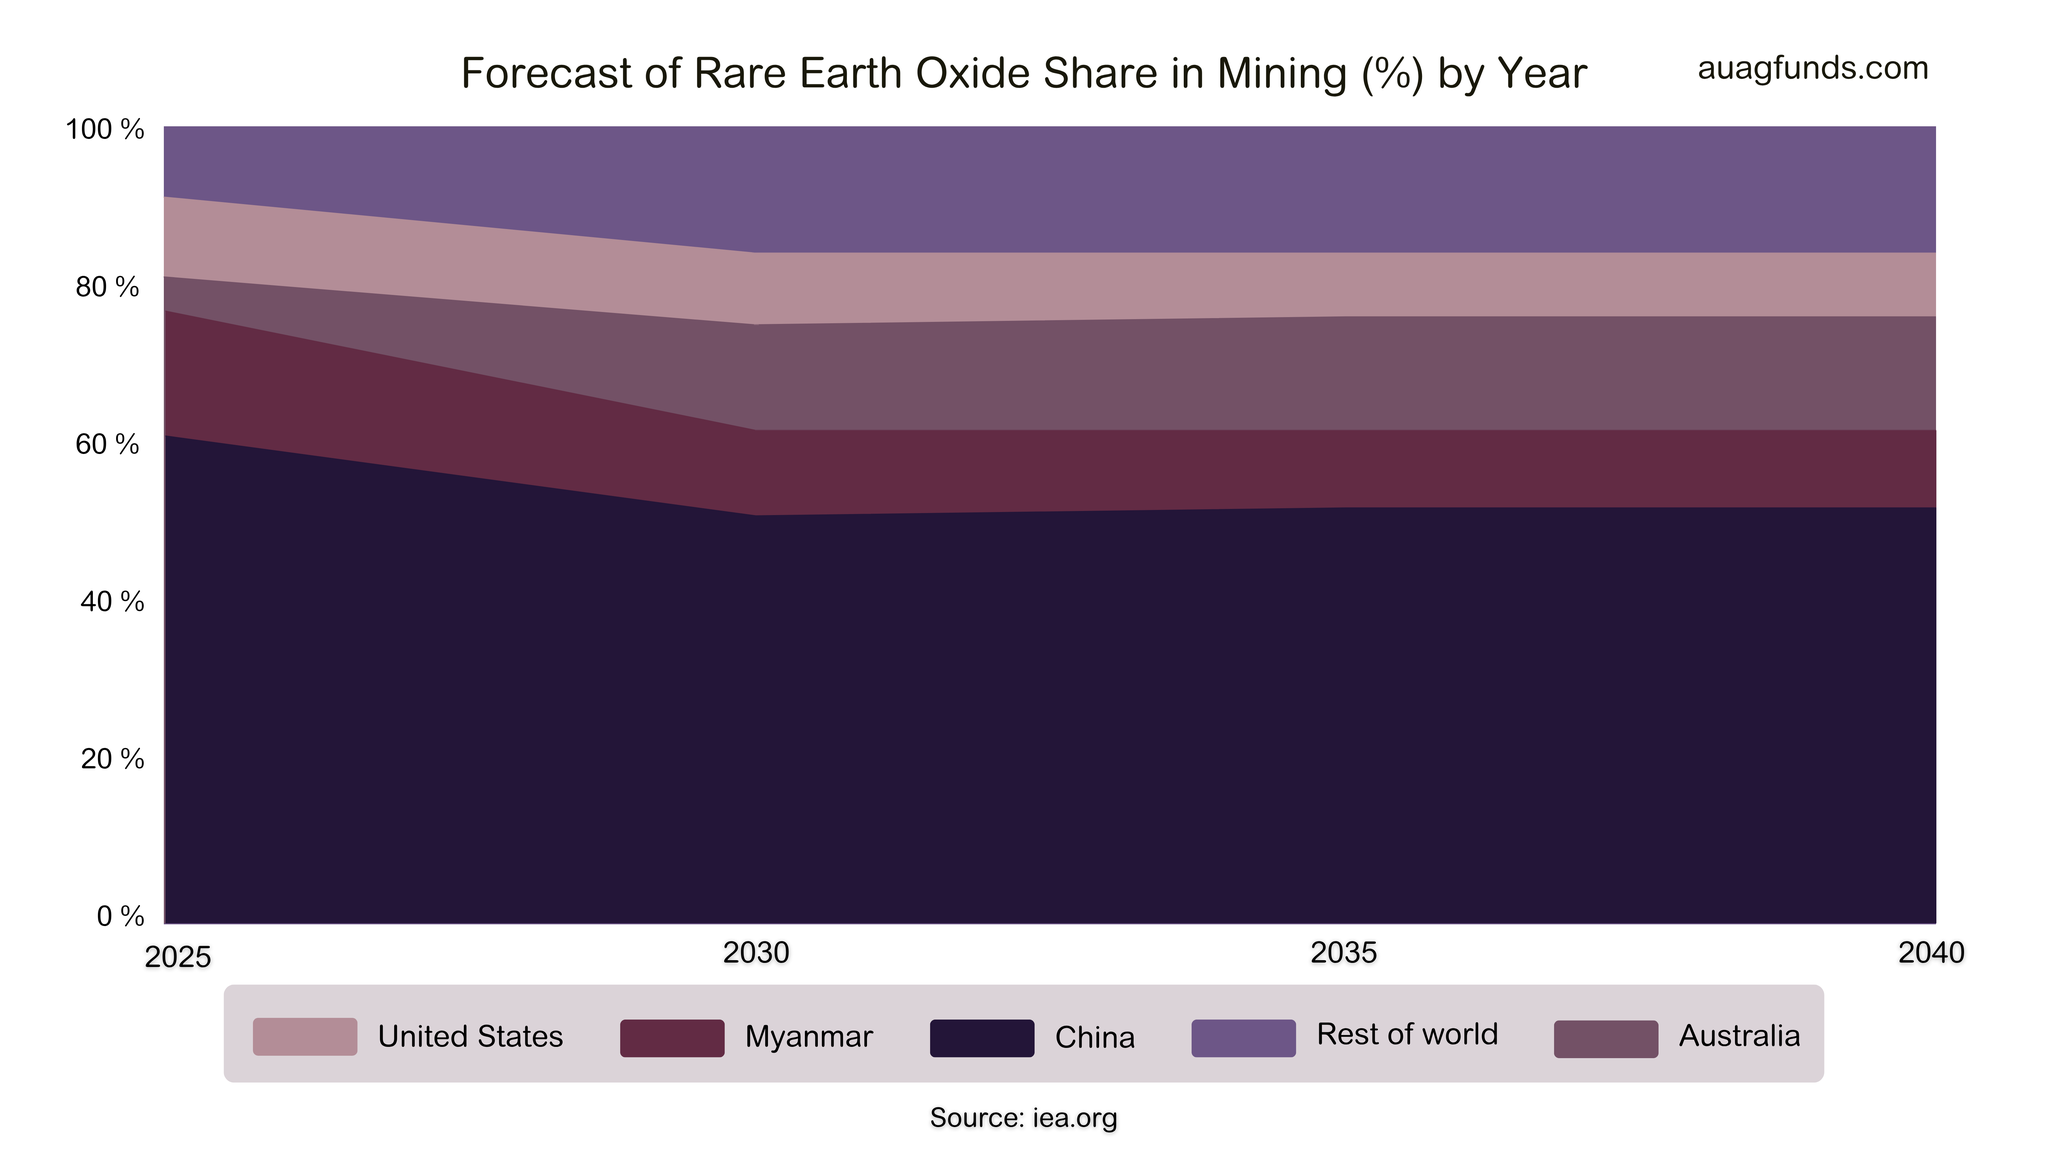
The chart below shows each country’s share of global Rare Earth Oxide mining, along with a forecast based on existing and confirmed future projects. Source: IEA.
From Industrial Policy to Geoeconomics (2024–2025)
In 2024, China entered a new phase as its rare earth policy acquired an explicitly geoeconomic character. The Regulations on the Management of Rare Earths (Order No. 785) established, for the first time, a comprehensive and security-classified framework placing the entire sector, from mining to export, under state control. The rules designated rare earths as state property, introduced production quotas and traceability requirements, and created a national reserve system to strengthen China’s resilience.
In 2025, control tightened further. On April 4, Announcement No. 18 introduced export licensing requirements for seven medium and heavy rare earth elements. Exporters must now apply to MOFCOM, disclose recipients and end-use, and customs authorities may detain shipments pending review. Although officially justified on environmental grounds, the timing coincided with Western technology restrictions and was widely interpreted as a retaliatory response.
During the summer, Beijing also imposed new production quotas without disclosing volumes, while the regulatory regime was extended to imported raw materials further down the chain.[ad3] Because a large portion of Western ore, especially from the U.S. and Australia, is still sent to China for refining, this effectively means these countries can no longer freely use their own material for defense or high-tech manufacturing.
On October 9, the next step followed: Ministry of Commerce Notice No. 61 extended export controls to five additional rare earth elements and advanced materials in magnet and semiconductor technologies. Companies using Chinese materials or technology must now demonstrate compliance to retain access, a mechanism that, in effect, makes control extraterritorial.
Together, these three measures form a coherent system granting China leverage across the entire rare earth supply chain. Since Western countries still lack industrial capacity for separation, metallization, and magnet manufacturing, Beijing can effectively control access even to materials mined elsewhere but refined within China. In just over a year, China’s rare earth policy has evolved from national regulation into a geoeconomic instrument with global reach where they have the ability to influence prices, flows, and availability of materials critical to Western industry and defense.
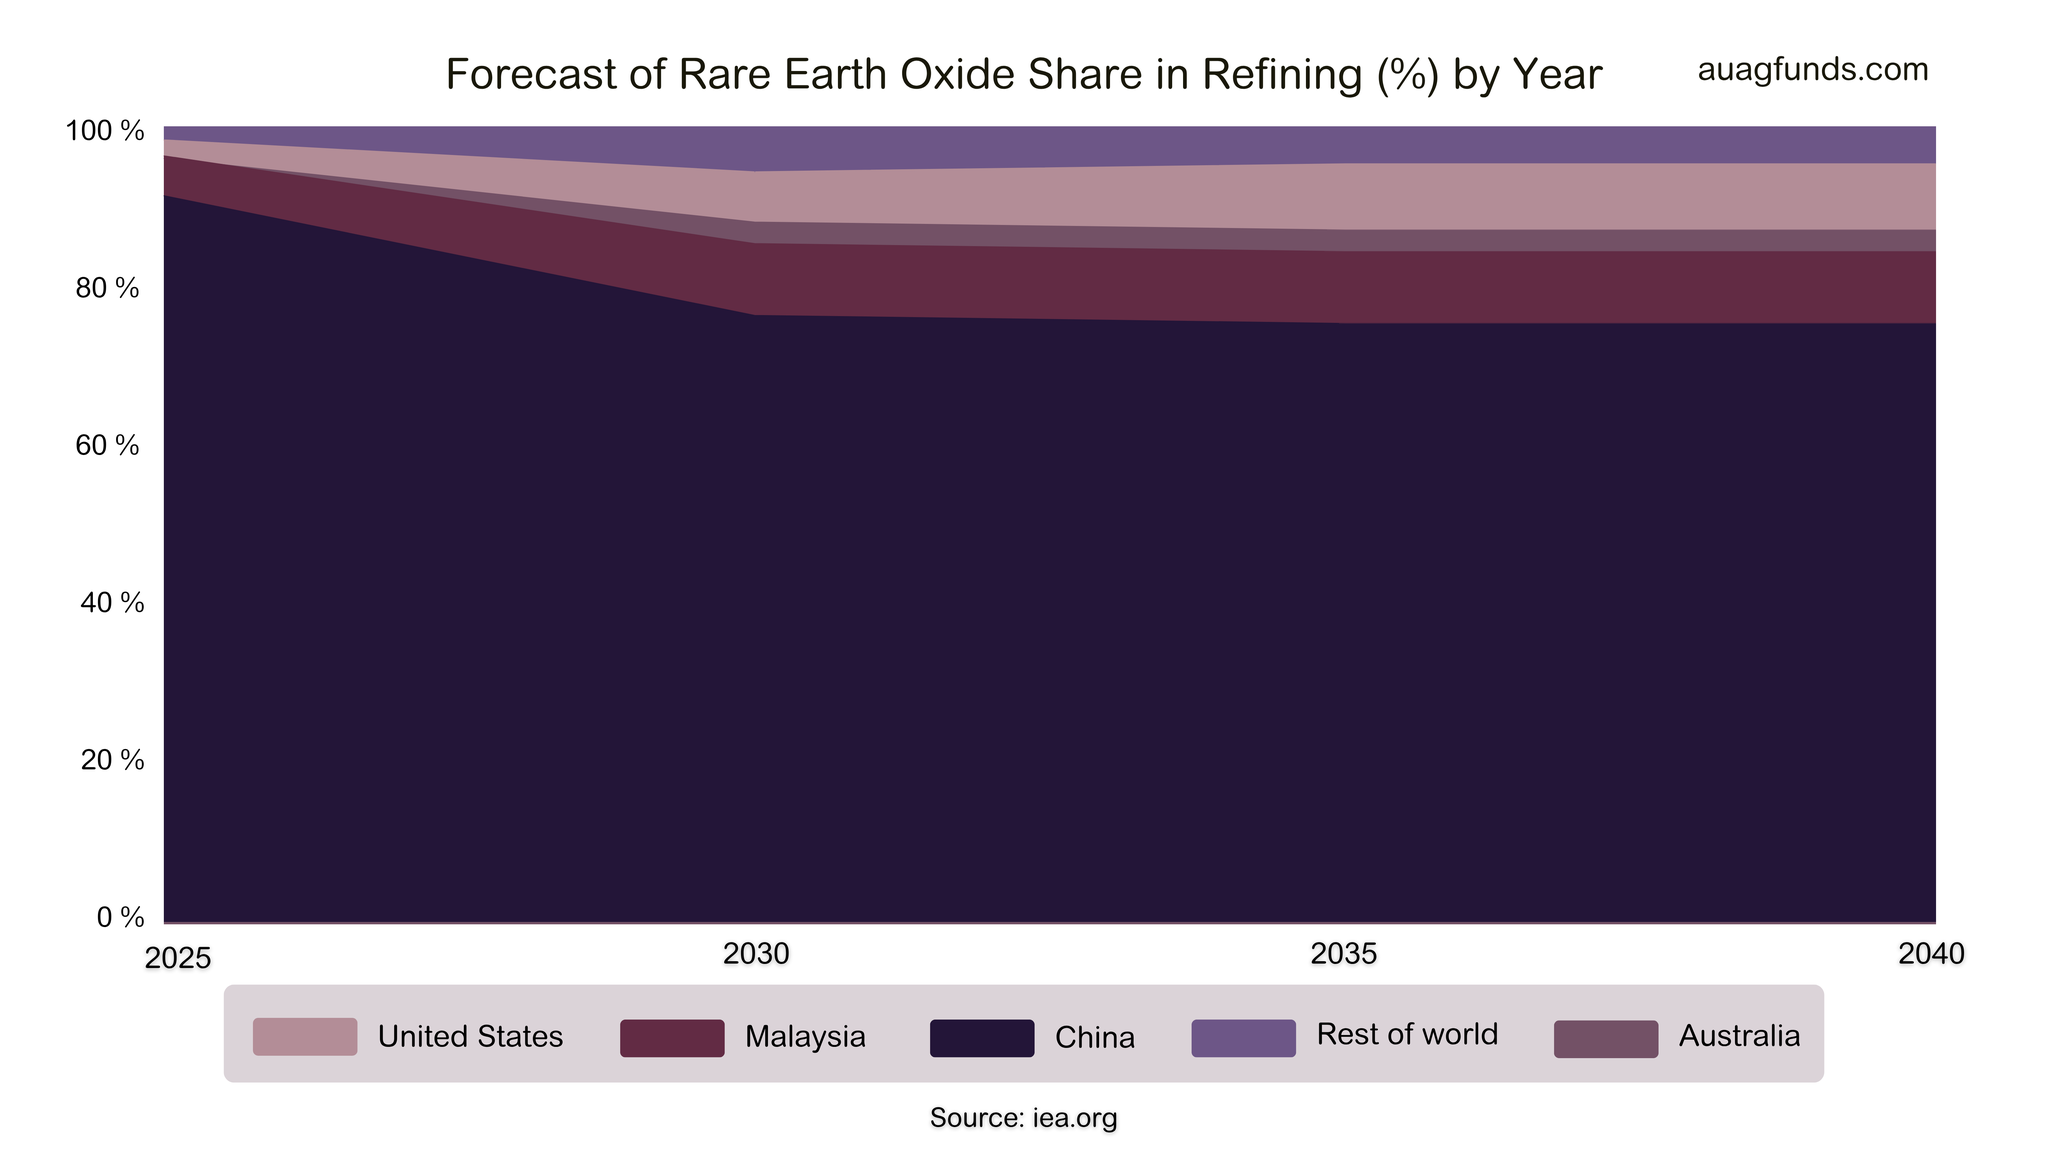
The chart below shows each country’s share of global Rare Earth Oxide refining (processing and separation), and a forecast based on existing and confirmed future projects. Source: IEA.
The West’s Industrial Policy Awakening
The U.S. and EU are now trying to reduce their dependence through initiatives such as the Inflation Reduction Act (IRA) and the Critical Raw Materials Act (CRMA) (see Article 2). Yet these efforts arrived late, after China had spent decades consolidating control across the entire REE value chain. The lead is now so significant that the West faces an industrial challenge of historic scale.
China’s dominance no longer rests solely on resource access, but on an institutionalized industrial structure characterized by strong state coordination, technological advantage, and vertical integration from mining to refining and manufacturing. For Western economies, achieving self-sufficiency will require political will, public investment, and long-term commitment.
At the same time, this imbalance is driving a new wave of industrial mobilization. The EU, U.S., and Australia are investing heavily in new mines, separation facilities, and refining capacity to reclaim control over strategic segments of the supply chain. For investors, this shift is fueling growing interest in companies that strengthen these links within the Western value chain, an area where policy, technology, and markets increasingly converge.
What Does This Mean for Investors?
China’s grip on the entire rare earth supply chain illustrates that industrial power depends as much on who refines and distributes resources as on where they are found.
Global markets, long driven primarily by economic factors, are now increasingly shaped by politics through regulations, export licensing, and state intervention that can rapidly shift both supply and demand. In this environment, the advantage lies with those who understand geoeconomic risk, how political decisions, trade tensions, and government policies shape the future conditions of industry.
AuAg Essential Metals invests in companies engaged in the extraction of industrial and technology metals (for example Rare Earth Metals, Uranium, Copper, and Lithium), providing exposure to the structural transformation now underway. As the West seeks to reduce its dependency on China and rebuild domestic value chains for strategic materials, the fund is positioned where new flows, technologies, and investments are set to converge.
This transition marks the beginning of a new industrial cycle, one in which the metals and manufacturing sectors become central to economic growth and technological innovation. For investors, it presents an opportunity to participate in the reindustrialization of the Western world.
By AuAg Funds
References
European Commission. (2023). Proposal for a regulation of the European Parliament and of the Council establishing a framework for ensuring a secure and sustainable supply of critical raw materials [COM(2023) 160 final]. Retrieved from: European Commission
European Commission. (n.d.). Critical raw materials act. Retrieved June 2025, from: Single Market Economy
European Council. (2024). *The European Union’s Strategic Agenda 2024–2029: *Consilium
Hool, A., Helbig, C., & Wierink, G. (2024). Challenges and opportunities of the European Critical Raw Materials Act. Mineral Economics, 37(3), 661–668: DOI
Reuters. (2025, June 4). Some European auto supplier plants shut down after China’s rare earth curbs.
Reuters. (2025, July 2). EU presses China on rare earths and Ukraine war ahead of summit.
Transport & Environment. (2023). EU strategic partnerships: How to shape secure, diverse and sustainable trade in critical minerals. [Briefing].
International Energy Agency (IEA). (2025). Critical Minerals Data Explorer. International Energy Agency (IEA)