Investing in rare earth metals | market, demand and exposure
Valuable insights
-
Rare earth metals are essential to the electrification of the economy – electric motors, electronics, robotics and defence systems.
-
Demand is expected to rise structurally as transport and industry electrify.
-
Supply is highly concentrated: China controls the bulk of the world's refining capacity, which leaves supply vulnerable to political decisions.
-
The West is therefore investing in a value chain of its own – mines, separation plants, magnet manufacturing and recycling – with active state support.
-
Rare earth metals cannot be bought as a commodity: there is no futures market and no physical fund.
-
Exposure comes instead through equities in the companies building the value chain, for example through a thematic equity fund.
The metals that electrify the economy
So what are rare earth metals? They are a group of 17 metallic elements – scandium, yttrium and the fifteen lanthanides. The name is partly misleading: the metals are not in fact particularly rare in the earth’s crust, and several are more common than copper or lead. What makes them “rare” is that they seldom occur in concentrated deposits, which makes mining, and above all refining, expensive and technically demanding.
The metals are divided into light (LREE) and heavy (HREE) rare earths. For anyone looking to invest in rare earth metals, four of them matter most: neodymium and praseodymium (NdPr) make up the volume in the permanent magnets (NdFeB) that drive electric motors, while dysprosium and terbium are the small but decisive additions that let the magnets withstand the high temperatures found in, for example, an electric car’s drivetrain. For these applications there are, in practice, no commercial substitutes.
The applications run right through the modern economy: drivetrains in electric vehicles, industrial motors and automation, robotics, hard drives and other electronics, wind turbines, medical technology such as MRI scanners and cancer treatment, and defence systems. What almost all of them have in common is the electrification of the economy. Demand is therefore expected to rise over a long period, independently of developments in any single sector.
What are NdFeB magnets?
NdFeB stands for neodymium-iron-boron – the strongest type of permanent magnet manufactured commercially. The magnets let electric motors be built small, light and efficient, and they are found in everything from electric cars and robots to headphones. Without the addition of dysprosium or terbium they lose their magnetism at the high temperatures found in, for example, an electric car's drivetrain.
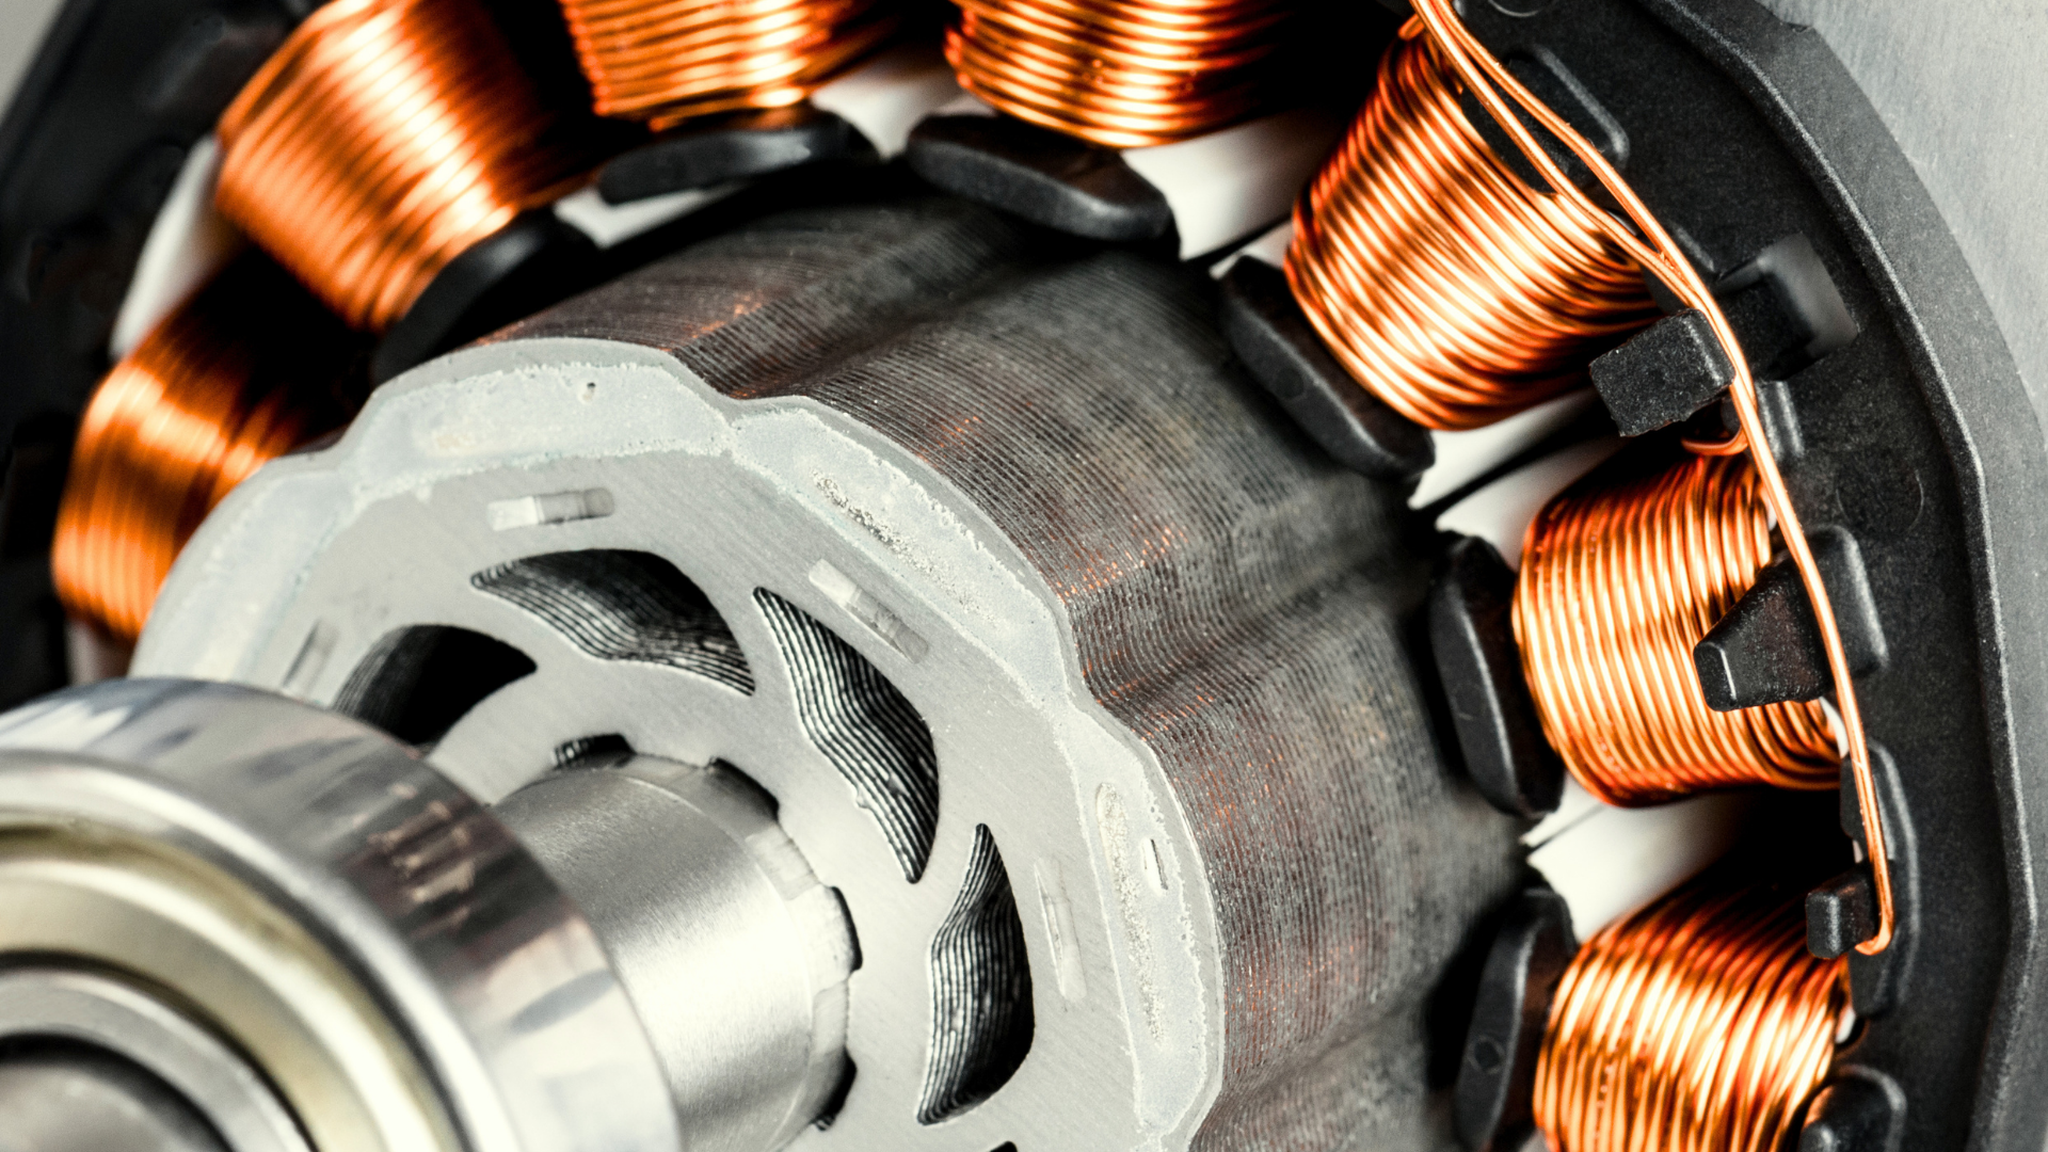
Permanent magnet motor rotor. The magnets on the shaft replace copper windings — and they need neodymium and dysprosium, which hold a far stronger magnetic field than common metals.
Demand, supply and refining
Demand for rare earth metals follows the electrification of the economy and is expected to grow over a long period. Supply is concentrated today. China accounts for an estimated 60–70 percent of global mining and around 85–90 percent of separation and refining capacity, and for certain heavy rare earths effectively all commercial capacity. Ore mined in the United States, Australia or Brazil has therefore largely been shipped to China for refining.
The combination of structurally growing demand and a supply that can be steered by political decisions is the background to the investment wave now under way in the West.
That refining ended up concentrated in China has historical explanations. For several decades capacity was built where costs were most favourable, and refining in the West was simply not profitable. Those conditions have changed in recent years. Electrification has broadened the customer base, industry and governments in Europe, North America and Japan want suppliers closer to home, and Chinese export licence requirements for rare earths and magnet materials have made origin a factor in industrial purchasing decisions.
The combination of growing demand and a clear interest in diversified supply has made it commercially viable to build a value chain in the West – from mine and separation to magnet manufacturing and recycling. That build-out is what lies behind the investment wave.
What does separation involve?
In the ore, the rare earths occur mixed with one another, and their chemical similarity makes them very difficult to separate. Separation takes hundreds of stages of liquid-liquid extraction and requires specialised technology, chemicals and years of experience. This is above all the stage that forms the value chain's real bottleneck, and where China has built its lead.
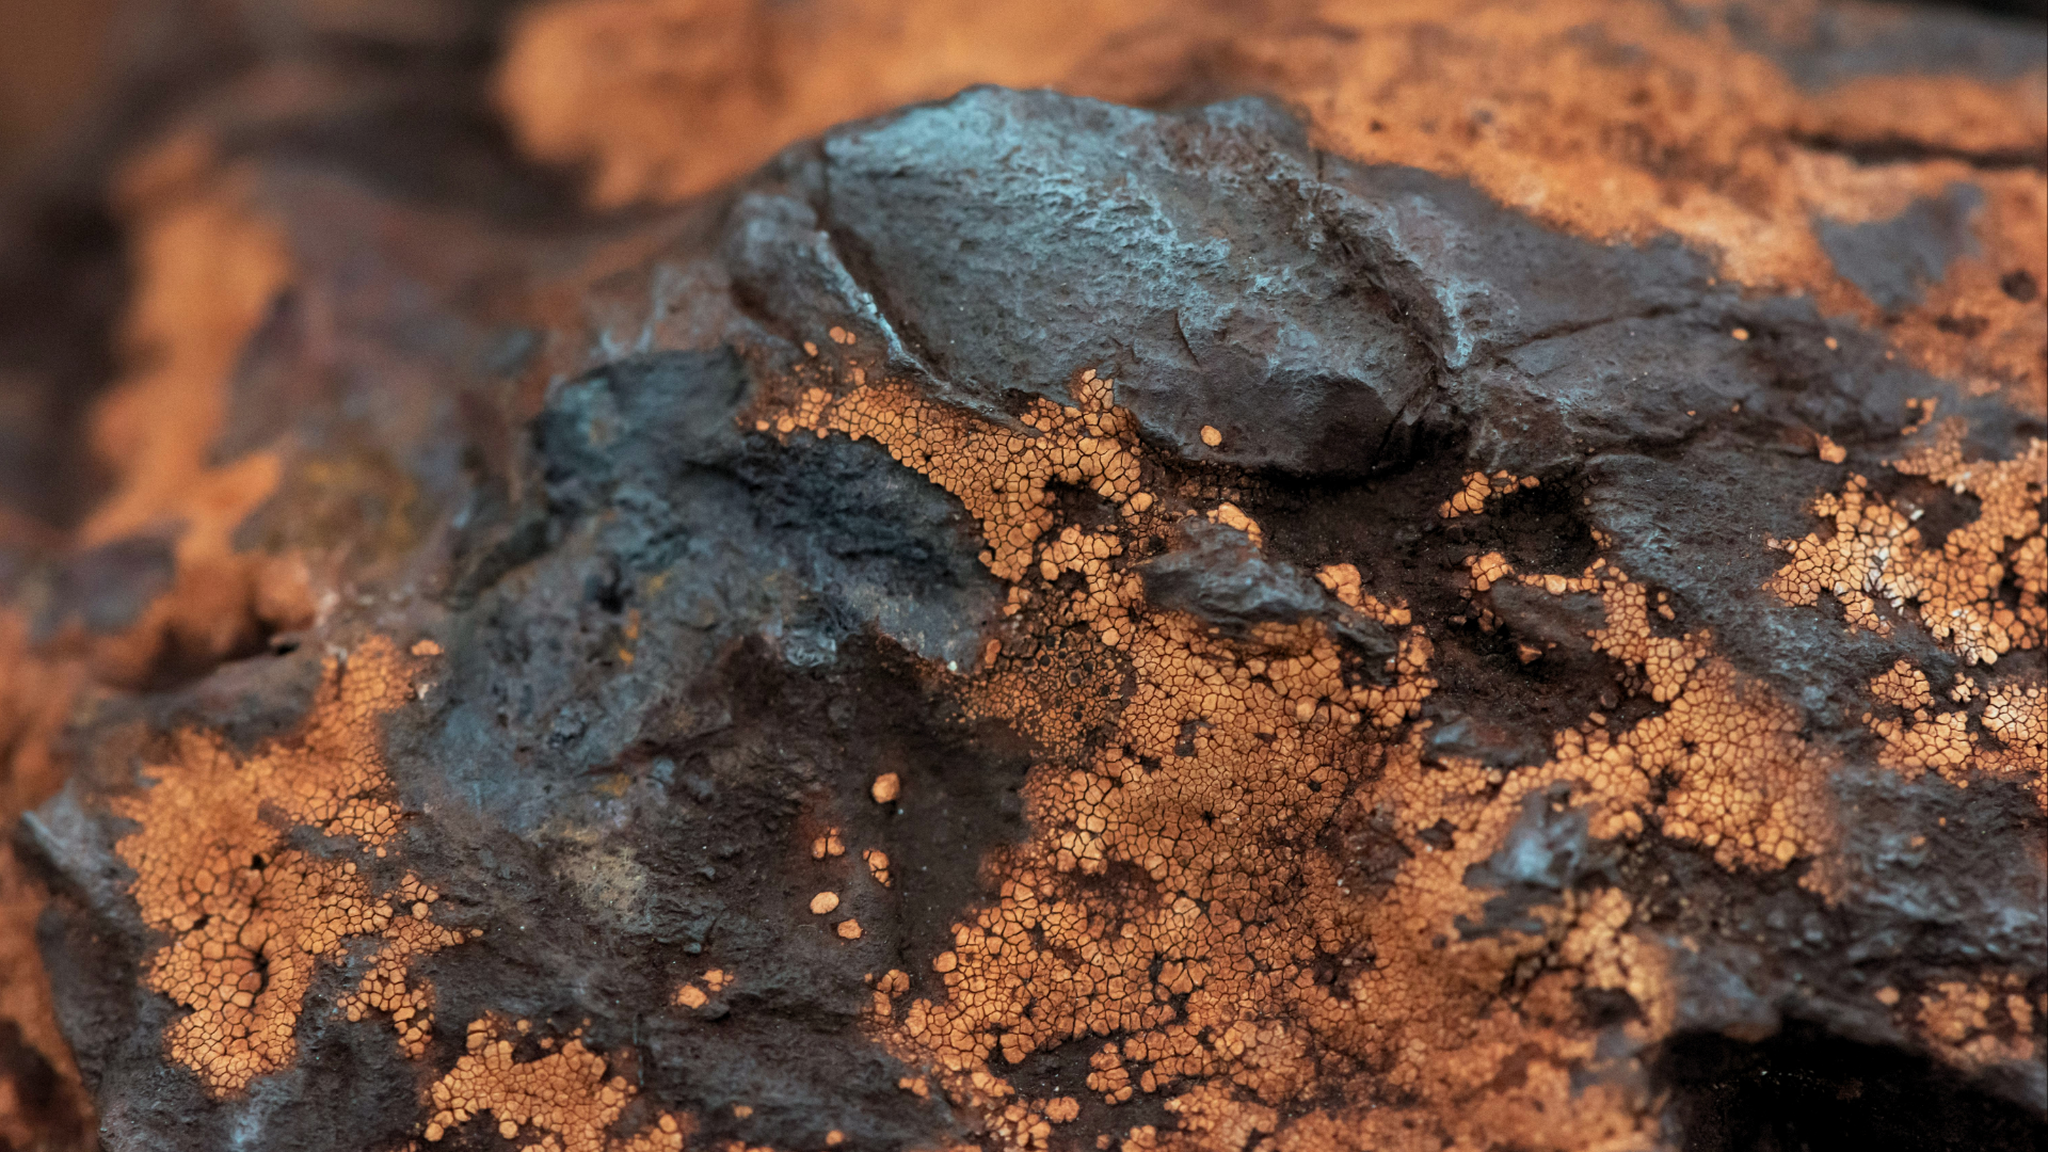
Iron ore. At Per Geijer in Kiruna the rare earth elements sit in apatite alongside the iron — Europe's largest known deposit, and a rare chance to produce them outside China.
Key risk factors in the market
The market for rare earth metals carries several types of risk that affect the companies in the value chain, and therefore investors seeking exposure:
-
Political decisions and export licences: Administrative decisions can change supply, prices and availability quickly – in China and in the West alike.
-
Price volatility and a two-tier market: The market is small and opaque; international prices can diverge sharply from Chinese ones, and even small changes in supply produce large price movements.
-
Jurisdictional risk: Where a company mines, refines and sells determines how exposed it is to export restrictions and trade conflicts.
-
Long lead times in refining: Building separation and magnet capacity takes many years and requires both technology and patient financing; new Western projects carry considerable execution risk.
The emergence of a Western value chain
Three forces are now converging:
- Demand is rising structurally with electrification.
- The West needs to diversify away from dependence on a single supplier.
- Capital, both state and private, is being directed for the first time in decades at every stage of the chain: mining, separation, magnet manufacturing and recycling.
The clearest shift is the state's new role in absorbing risk. In the United States, the Department of Defense has taken an ownership stake in the country's leading producer, guaranteed a price floor for NdPr of 110 dollars per kilo and financed new separation and magnet capacity. The EU's Critical Raw Materials Act (CRMA) sets targets for 2030 – at least 10 percent domestic extraction, 40 percent domestic refining and 25 percent recycling of strategic raw materials, and no more than 65 percent from any single country – and has been followed by further programmes for stockpiling and joint purchasing.
Japan showed how the model works in the years after 2010: state financing, guaranteed purchase agreements and strategic stockpiles built up an alternative supply that is today the template for both the United States and the EU.
Capacity is now being built in practice. In 2025 the first commercial separation of dysprosium and terbium outside China in decades came on stream, in Malaysia using Australian ore, while plants in France and the United States have begun producing magnet-grade NdPr. Magnet manufacturing is being established in North America and Europe, and a growing recycling industry recovers magnet metals from end-of-life electric motors, hard drives and electronics.
What are price floors and offtake agreements?
A price floor means the state guarantees the producer a minimum price – if the market price falls below that level, the state covers the difference. An offtake agreement is a commitment to buy future production on predetermined terms. Together they remove the price risk that previously made it impossible to finance Western plants in competition with China.
Investing in rare earth metals
Unlike gold or copper, rare earth metals cannot be traded as a commodity. There is no functioning futures market and no exchange-traded product that holds physical metal. Trading takes place mainly through long-term agreements between producers and industrial customers.
Exposure to rare earth metals therefore arises through the companies in the value chain – that is, through equities rather than the commodity itself:
- Mining companies and producers that mine and concentrate the ore
- Refining and separation companies that convert concentrate into usable oxides and metals
- Magnet and component manufacturers that account for the stage where most value is added
- Recycling companies that recover the metals from end-of-life products
The return therefore comes from the companies’ earnings and development, not directly from metal prices, even though prices affect company profitability.
How to invest in rare earth metals through an exchange-traded fund
Investment in rare earth companies is often made through thematic equity funds or ETFs. Individual companies in the sector can be small, volatile and dependent on single projects or permits. A fund gives broader exposure by spreading value across several companies, several stages of the value chain and several geographies. For anyone looking to benefit from the build-out of the Western value chain, the jurisdictions in which a fund’s holdings operate are also relevant: the character of the exposure is determined by where the companies mine and refine, not only by what they produce.
The key points
Demand for rare earth metals is growing structurally with the electrification of the economy, while supply is concentrated in a single country and can be steered by political decisions. The West is responding by building a value chain of its own – from mine to magnet and recycling – with state support in the form of ownership stakes, price floors and guaranteed purchase agreements. Since the metals cannot be owned as a commodity, exposure comes through equities in the companies building that chain.
In the Swedish market there are equity funds, such as AuAg Essential Metals, whose focus on industrial and technology metals means the fund may include companies connected to the rare earth value chain. The fund invests in equally weighted holdings and prioritises companies in stable jurisdictions. Any such exposure relates to the companies’ operations and not to direct ownership of the metals as a commodity.
Frequently asked questions about rare earth metals
Above all in permanent magnets for electric motors – in electric vehicles, industry, robotics and wind power – and in electronics, medical technology and defence systems. Four metals dominate demand: neodymium, praseodymium, dysprosium and terbium.
No, several of them are more common than copper in the earth's crust. The difficulty is that they seldom occur in concentrated form, which makes extraction and refining expensive and technically complicated. The bottleneck is refining, not occurrence.
No. There is no futures market and no physical exchange-traded product, and a Swedish fund cannot own the metals directly. Exposure comes through equities in companies that mine, refine, manufacture magnets or recycle the metals.
Yes. LKAB's Per Geijer deposit in Kiruna is one of the largest known in Europe, and the company is also developing extraction from residual streams of iron ore production. Norway has the Fen Complex. Commercial production is, however, several years away.
In practice through equities or equity funds. A thematic fund focused on industrial and technology metals can provide diversified exposure across several companies and several stages of the value chain.
Disclaimer
This material is marketing communication. The information does not constitute investment advice or a personal recommendation. Investment decisions should be based on the fund’s information brochure and fact sheet, as well as your own considerations. Investments involve risk. Past performance is not a guarantee of future returns. The money invested in the fund may both increase and decrease in value, and it is not certain that you will recover the entire amount invested. Before making an investment decision, you should review the fund’s information brochure and fact sheet.
