Intro
The market for metals and mining companies has remained strong throughout the month. The funds have reached several new all-time highs (ATH), we have seen large net inflows, and welcomed several thousand new investors. In addition, our assets under management surpassed the milestone of 4 billion SEK. In this month’s letter, we comment on the rise in gold and silver prices and the performance of mining companies. We also look ahead to the final quarter of the year. Keep reading the monthly letter below.
Au and Ag during the previous month
The gold price closed the month at USD 3,859 (3,449), rising almost 12% in September.
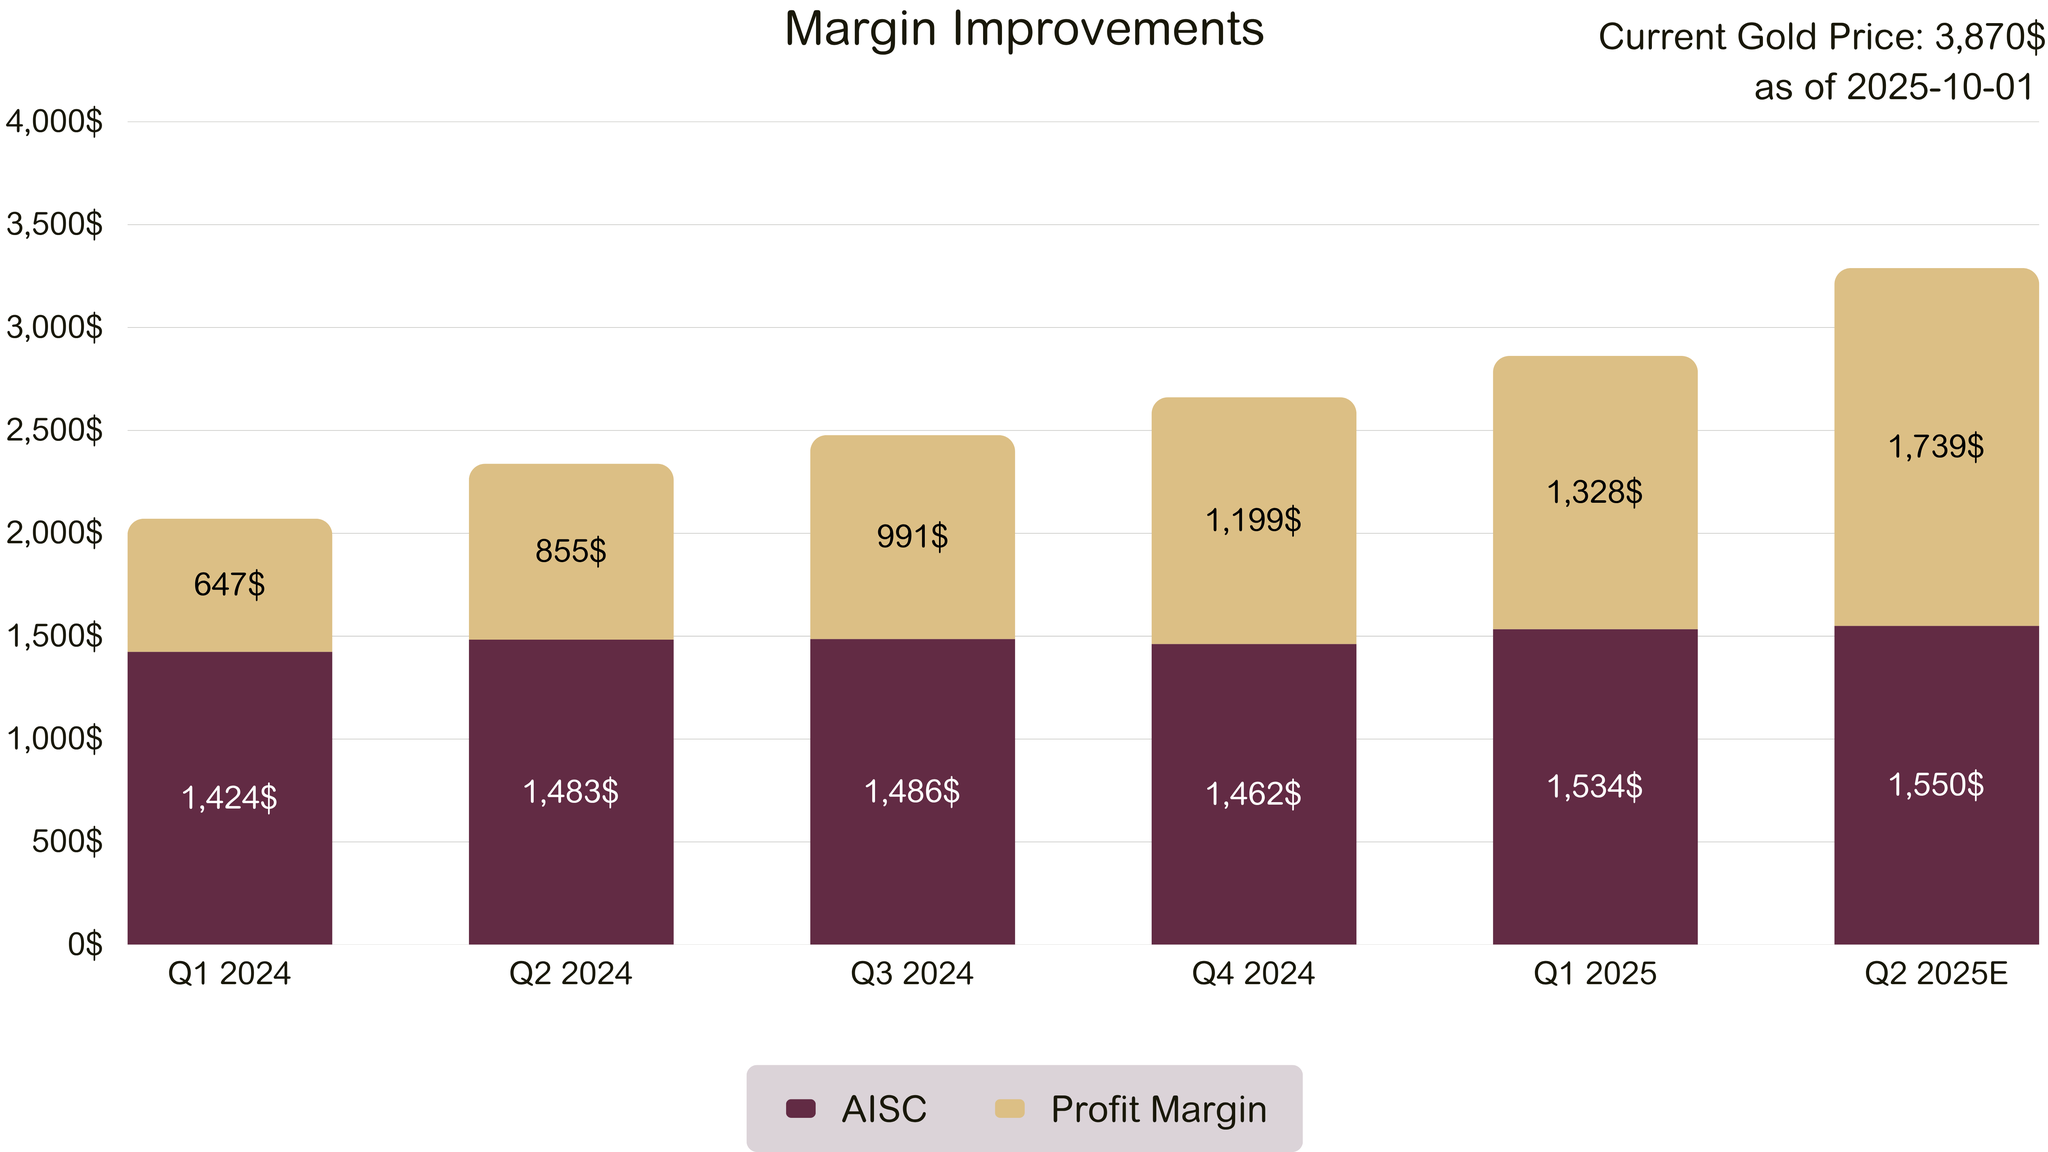
The price surged straight through the 3,500–3,600 range and has now established itself above 3,800, setting the stage for the next major level at 4,000. A gold price of 4,000 may sound high, but we consider it still well below where it should be. With global banks such as JPMorgan and Goldman Sachs also using both 4,000 and 5,000 in their scenarios, it increasingly looks like this is becoming the “new normal.”
The Fed’s first rate cut in a long time was one driver, but more importantly, it is clear that the current president holds the power and usually gets his way, one way or another. Moreover, we believe the Fed will need to cut rates significantly for reasons beyond presidential pressure. Quantitative easing (QE) will also likely be required to bring down long-term yields that are weighing on the U.S. economy. The day QE returns, the next target of 5,000 will be firmly in sight.
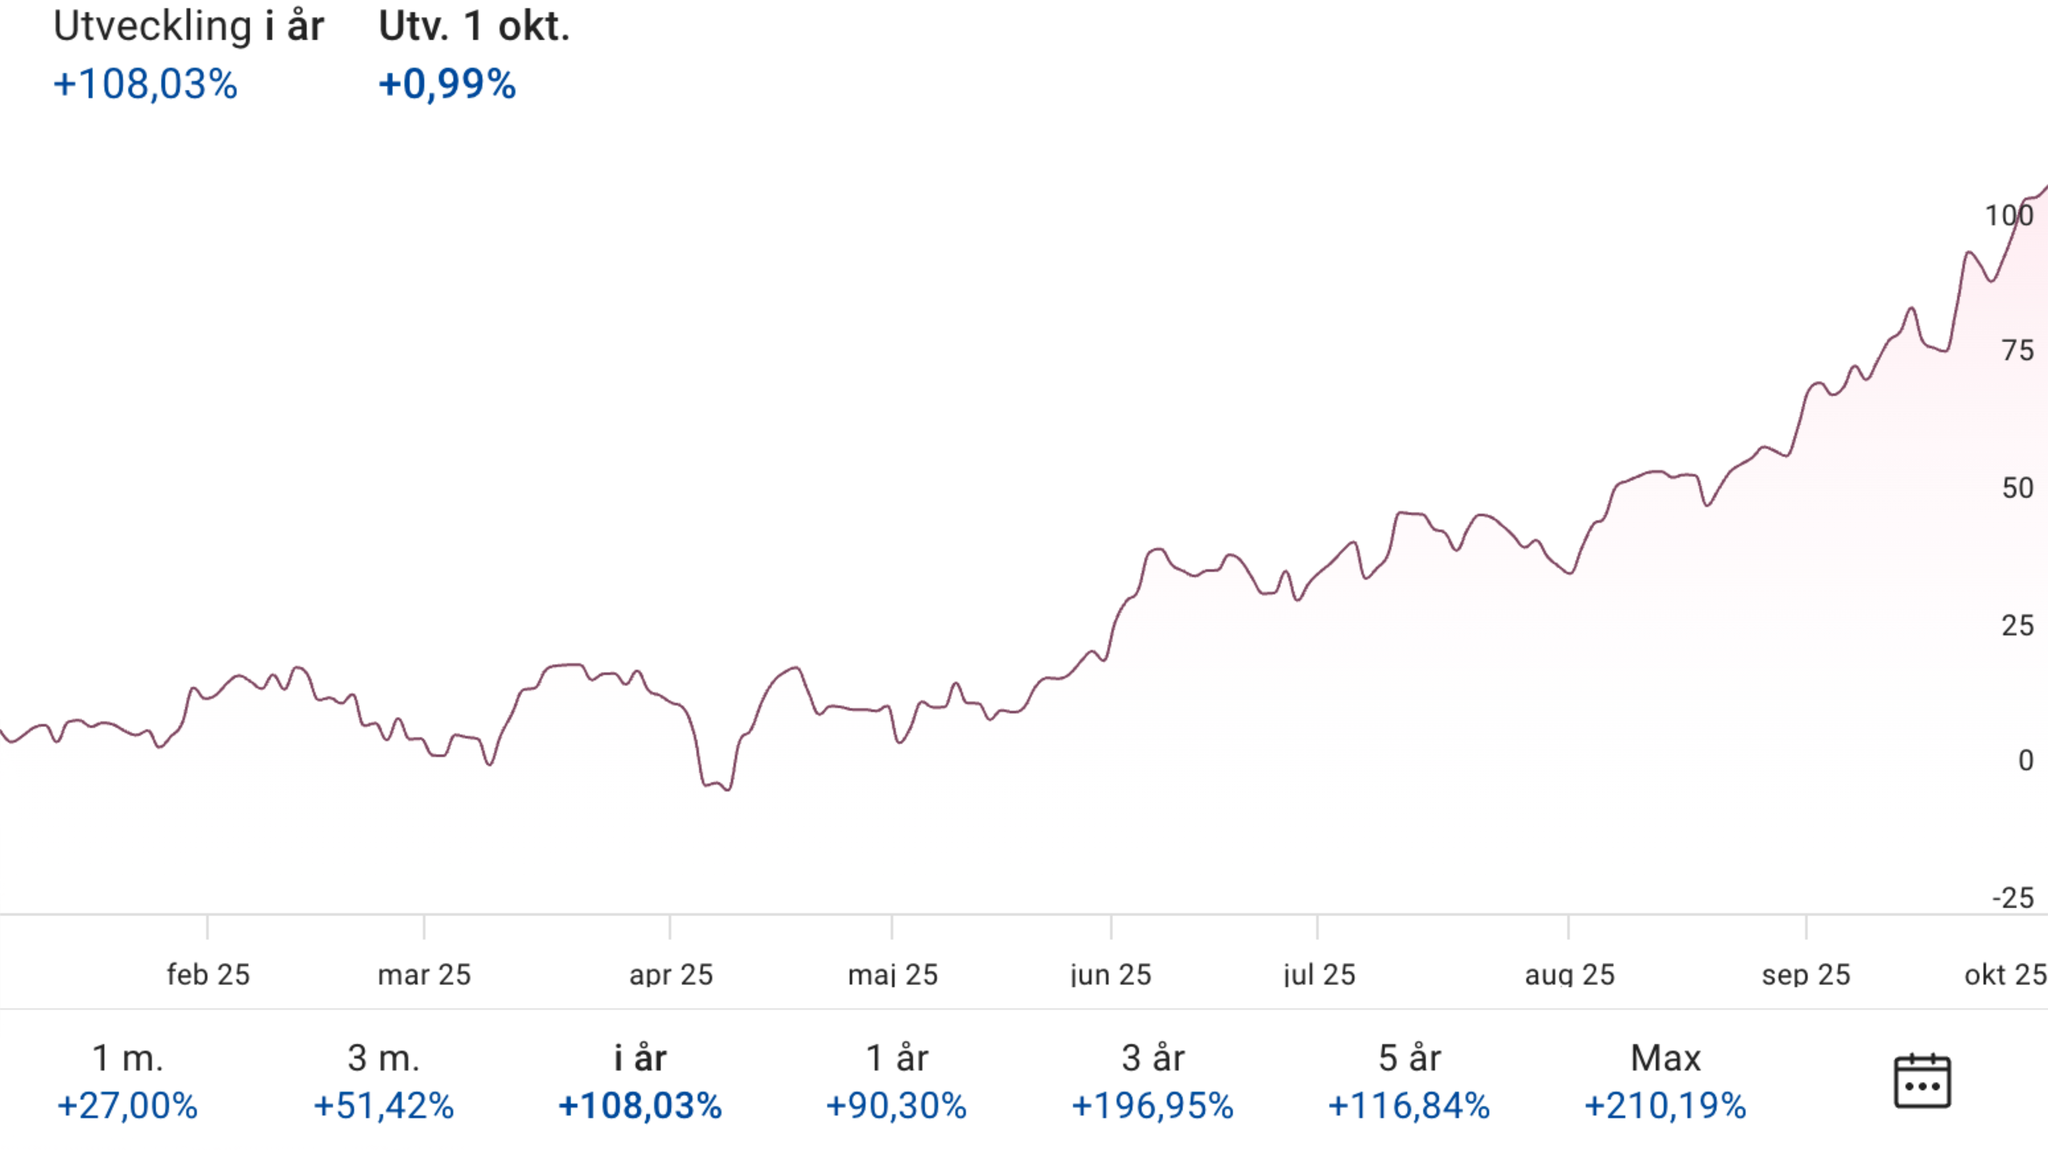
The U.S. dollar has lost -15% against the SEK (-13% against the EUR) in 2025. This means that while the gold price is up +47% in USD, it has risen +25% in SEK (+30% in EUR). It is this latter figure that should be compared with the AuAg Gold Rush fund, which is up +88% in SEK (+95% in EUR). Measured in USD, the fund has gained +109% this year.