Au and Ag in the past month
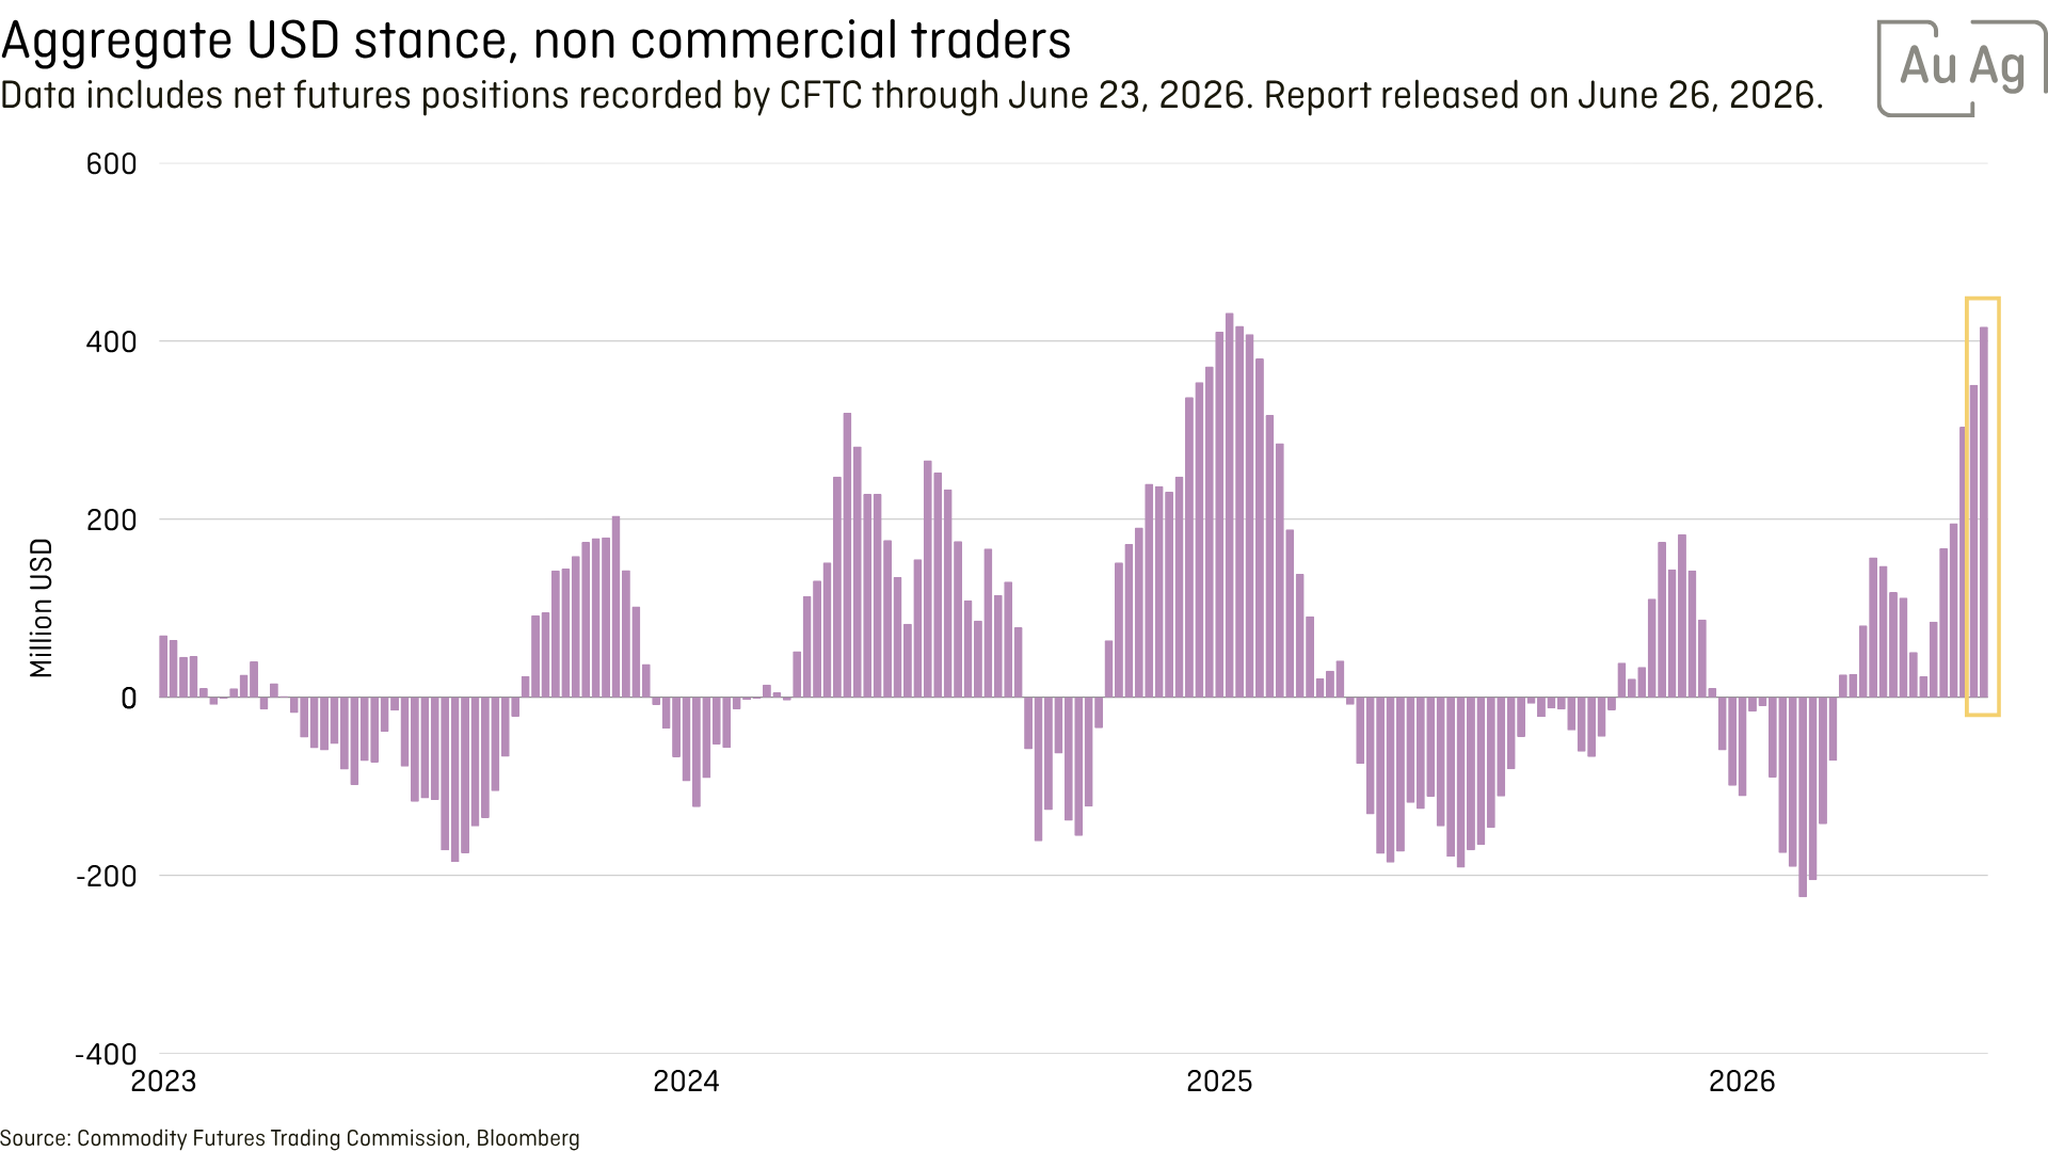
Market expectations of Fed rate hikes have, over the past few months, pushed many toward the dollar, creating a clear headwind for gold. Gold ended the month at USD 4,007 per troy ounce, down −11.7% from USD 4,540. At the same time, the dollar index has risen sharply and the dollar is now extremely overbought — a setup that likely will lead to a reversal going forward.
Underlying factors (debt reaching new record highs and enormous budget deficits with more and more unfunded projects) continue to be strong fundamental drivers for materially higher gold prices.
As soon as the market also recognizes the difficulty of raising rates into a “cost-push inflation,” and that the U.S. simultaneously has to bring long-term rates down, a new trend for the gold price will take off again. It is precisely the level of long-term rates that makes the cost of America’s enormous debt such a heavy burden.
At the same time, following confiscations and trade wars, many countries are now showing less interest in buying U.S. Treasuries. The Iran war has also hurt several Arab countries, countries that had expected more of the promised protection under the Petrodollar arrangement. Combined with reduced oil production and lower trade surpluses, further purchasing power is disappearing. That makes it harder for the U.S. to keep financing its ongoing budget deficits.
To press long-term rates lower, an excess of bond buyers is needed. If that demand isn’t there in the market, the Fed will have to step in as “the buyer of last resort.” Once we see some form of quantitative easing again, gold prices will rise to new all-time highs (above USD 5,594 per troy ounce). With the mid-year mark behind us, we may be at the start of that move. Once it takes off, many will be surprised how quickly it can travel.
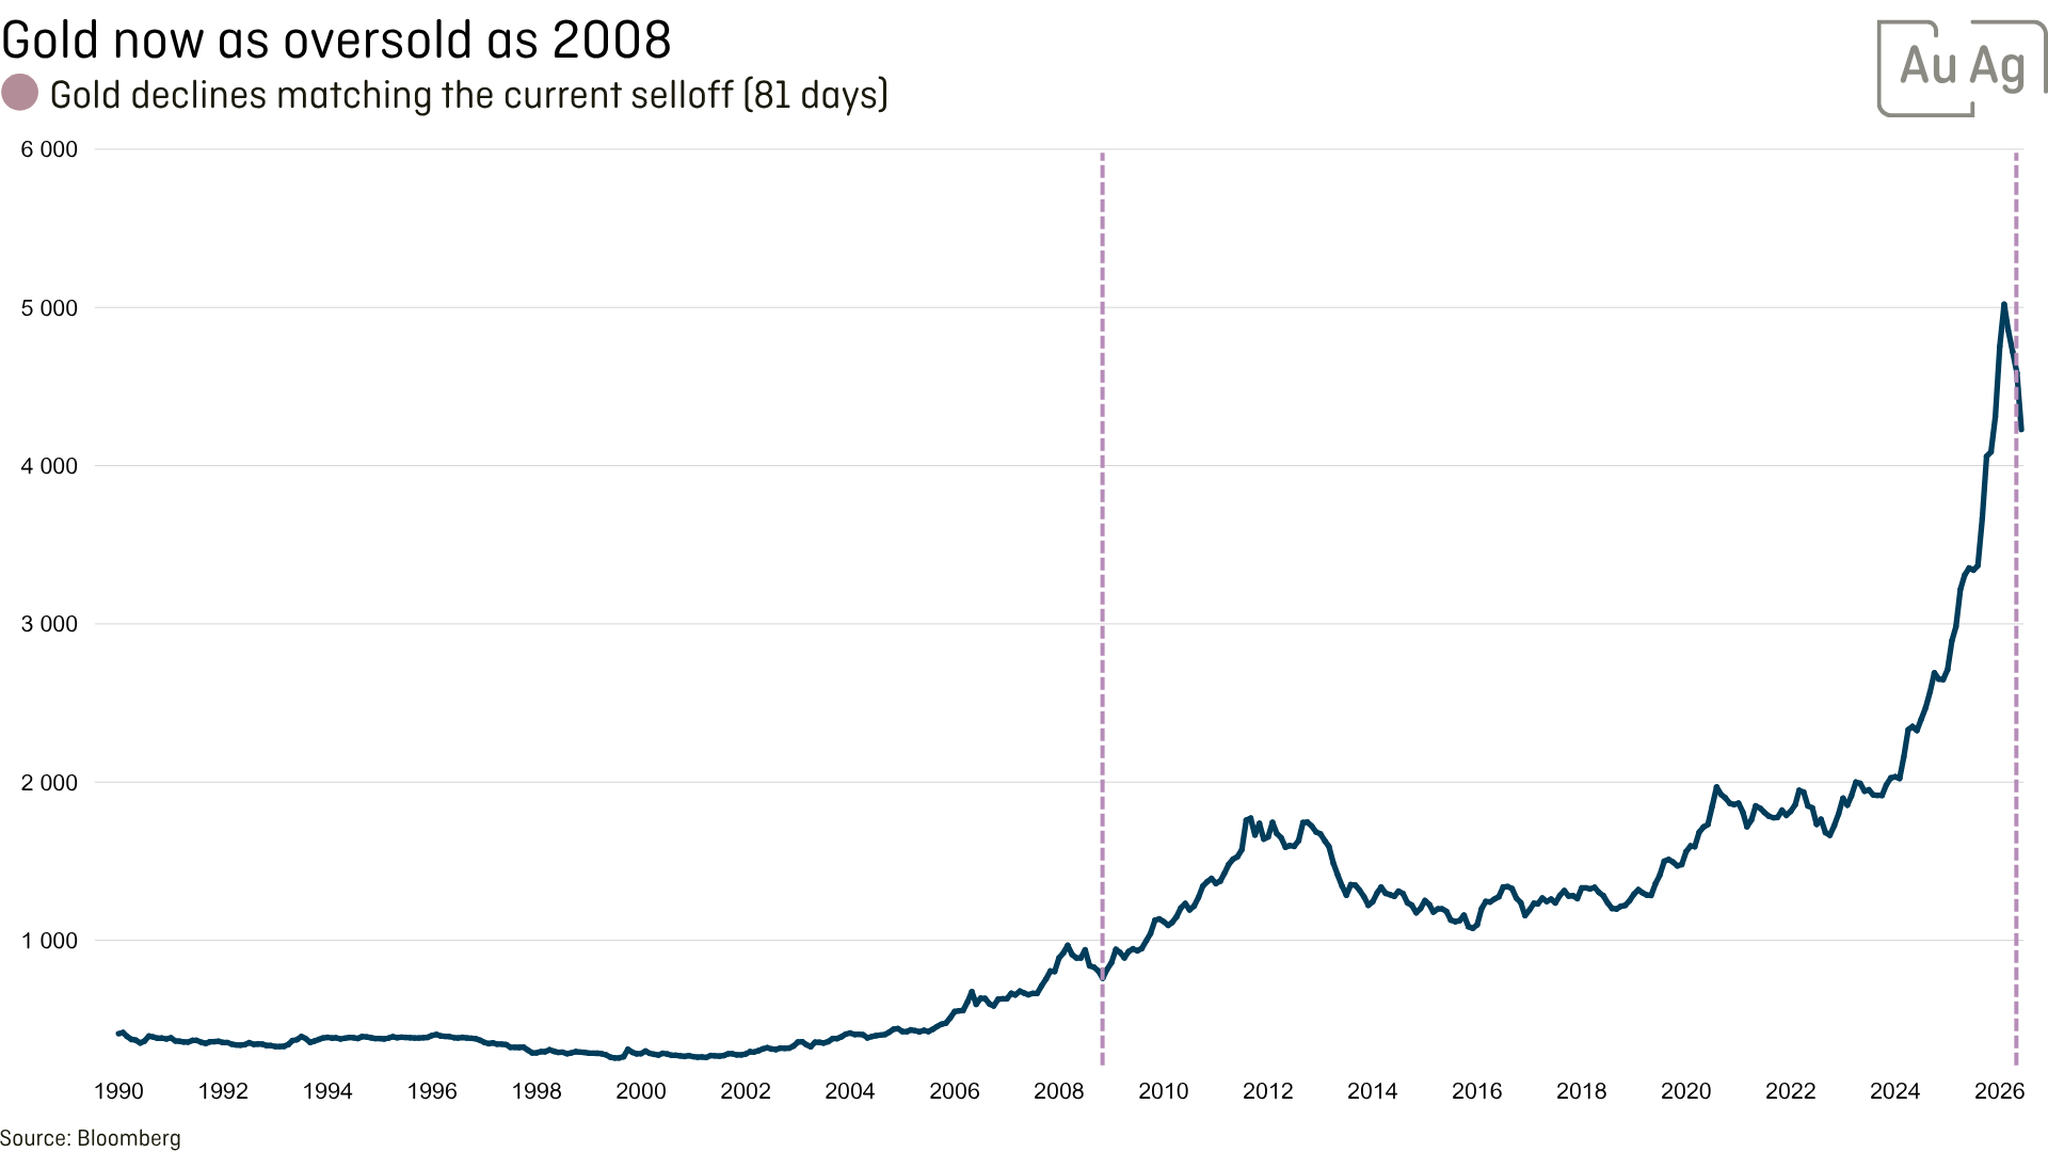
Gold is now also as oversold as it was during the financial and debt crisis of 2008. As always, after long periods of rising prices, sharp corrections of 20–30% are normal before the next upswing takes hold.